Emergency Fund: How Much You Need & How to Build It
An emergency fund is money you can use when an unexpected cost or interruption to income would otherwise leave you unable to pay for essentials. The right target depends on your expenses, responsibilities, and access to reliable income. A single dollar amount cannot fit every household.
Updated September 28, 2026. Examples below use U.S. dollars. Deposit-insurance information applies to U.S. banks; readers elsewhere should check their local protection scheme. This is general education, not a personalized savings recommendation.
Start with a manageable first goal
The Consumer Financial Protection Bureau recommends considering the unexpected expenses you have faced before when setting a savings goal. Even a small reserve can help; there is no universal $1,000 minimum.
For example, if a $300 repair would disrupt your ability to get to work, you could make $300 your first milestone. Saving $25 each week would reach it in 12 weeks, assuming no withdrawals and ignoring interest. Your own milestone may be smaller or larger.
Calculate the monthly costs you would need to cover
Use a realistic list of essentials: housing, basic food, utilities, necessary transport, insurance, medical needs, and minimum required debt payments. Do not count the same cost twice. Decide which subscriptions or discretionary costs you could actually stop during an income interruption.
| Illustrative essential expense | Monthly amount |
|---|---|
| Housing and utilities | $1,200 |
| Groceries and household basics | $350 |
| Necessary transport | $250 |
| Insurance and medical costs | $250 |
| Minimum debt payments | $150 |
| Total essentials | $2,200 |
For this example household, one month of essentials is $2,200, three months is $6,600, and six months is $13,200. These are scenarios to compare, not a rule prescribing how much the household must save.
A longer possible job search, dependents, unstable earnings, or large insurance deductibles may justify testing a larger reserve. Reliable income from another household member may change the calculation. There is no validated rule here that each risk requires an extra $1,500 or a fixed number of months.
Turn the target into a realistic saving schedule
Suppose the example household has $600 saved and chooses $2,200 as its next milestone. The gap is $1,600. At $100 per month, that takes 16 months; at $200, it takes eight months. If a $400 expense occurs along the way, it adds four or two months respectively, assuming contributions stay unchanged. Interest is excluded for simplicity.
Use the calculation: remaining goal ÷ affordable contribution = number of saving periods. Round up if the result is not a whole period. If the affordable contribution is zero, start by reviewing your household budget; a forced transfer that causes missed bills does not improve resilience.
Keep uncertain resources separate from cash already saved. A possible severance payment, family loan, or unused credit limit may not be available when needed. List their conditions and timing before relying on them.
Choose an account for access and safety
Compare withdrawal access, fees, minimum balances, transfer times, and deposit protection. A separate savings account can make the reserve easier to track, but first check how you would access money on a weekend or during an urgent expense. Interest rates can change, so this guide does not promise a current APY or endorse a particular bank.
At an FDIC-insured U.S. bank, standard coverage is $250,000 per depositor, per insured bank, per ownership category. It is not a fresh $250,000 limit for every savings account. See the FDIC’s deposit-insurance FAQs for the rules and exceptions.
For money you might need immediately, avoid assuming that a product with a lockup, withdrawal penalty, or fluctuating market value can substitute for accessible cash. Check the actual terms before placing emergency money in it. A higher advertised yield alone does not establish suitability.
Decide when to use the fund
Ask whether the expense is necessary, unexpected, and time-sensitive. A sudden essential repair or income loss may qualify. Planned holidays and known annual bills belong in separate savings categories. Do not postpone urgent medical care or safety repairs simply to obey an arbitrary waiting period.
If you use the money, record the amount and recalculate the next savings milestone. Using the reserve for its intended purpose is not a failure. Replenish at an affordable pace while continuing to cover essential bills and required payments.
Common questions
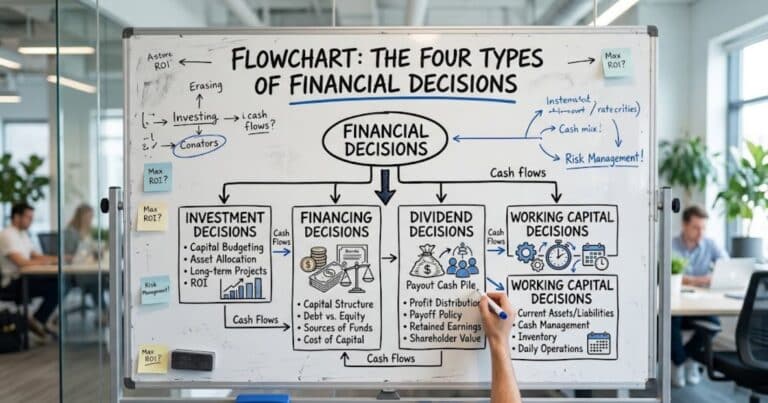
For a broader way to weigh savings priorities, read about the types of financial decisions. If you are also considering investing, our first-time investing guide discusses preparation and time horizons.
Is $10,000 enough? Divide it by your essential monthly expenses. At $2,200, it covers about 4.5 months before any separate one-off costs. At $4,000, it covers 2.5 months. Whether either is enough depends on the risks you are planning for.
Is $20,000 too much? There is no universal upper limit measured in months. Consider access needs, income uncertainty, other obligations, and the trade-off between holding cash and funding other goals. Do not treat six months as an automatic instruction to invest the rest.
Should I save while repaying debt? Keep required payments in the budget. Beyond those, the balance between a cash buffer and extra repayments depends on interest costs, income stability, and how another unexpected expense would be covered. A professional familiar with your circumstances can help with that trade-off.
One Comment